Preliminary Results for November 2026
| Nov | Oct | Nov | M-M | Y-Y | |
| 2026 | 2026 | 2025 | Change | Change | |
| Index of Consumer Sentiment | 51.0 | 48.0 | 51.0 | +6.3% | +0.0% |
| Current Economic Conditions | 51.0 | 46.7 | 51.1 | +9.2% | -0.2% |
| Index of Consumer Expectations | 50.9 | 48.8 | 51.0 | +4.3% | -0.2% |
Read our special reports:
10/30/26
Expected Outcomes and Economic Implications of Midterm Elections10/23/26
Risks of Entrenchment: Long-Run Inflation Expectations in Recent and Longer Historical Context10/9/26
Gasoline Prices and Expected Consumer Spending7/10/26
Sentiment, Web-Based Data Collection, and Partisanship5/22/26
National Estimates Continue to Align With Views of Independents5/8/26
Confidence in Financial Institutions
Next data release: Friday, November 20, 2026 for Final November data at 10am ET
Surveys of Consumers Director Joanne Hsu
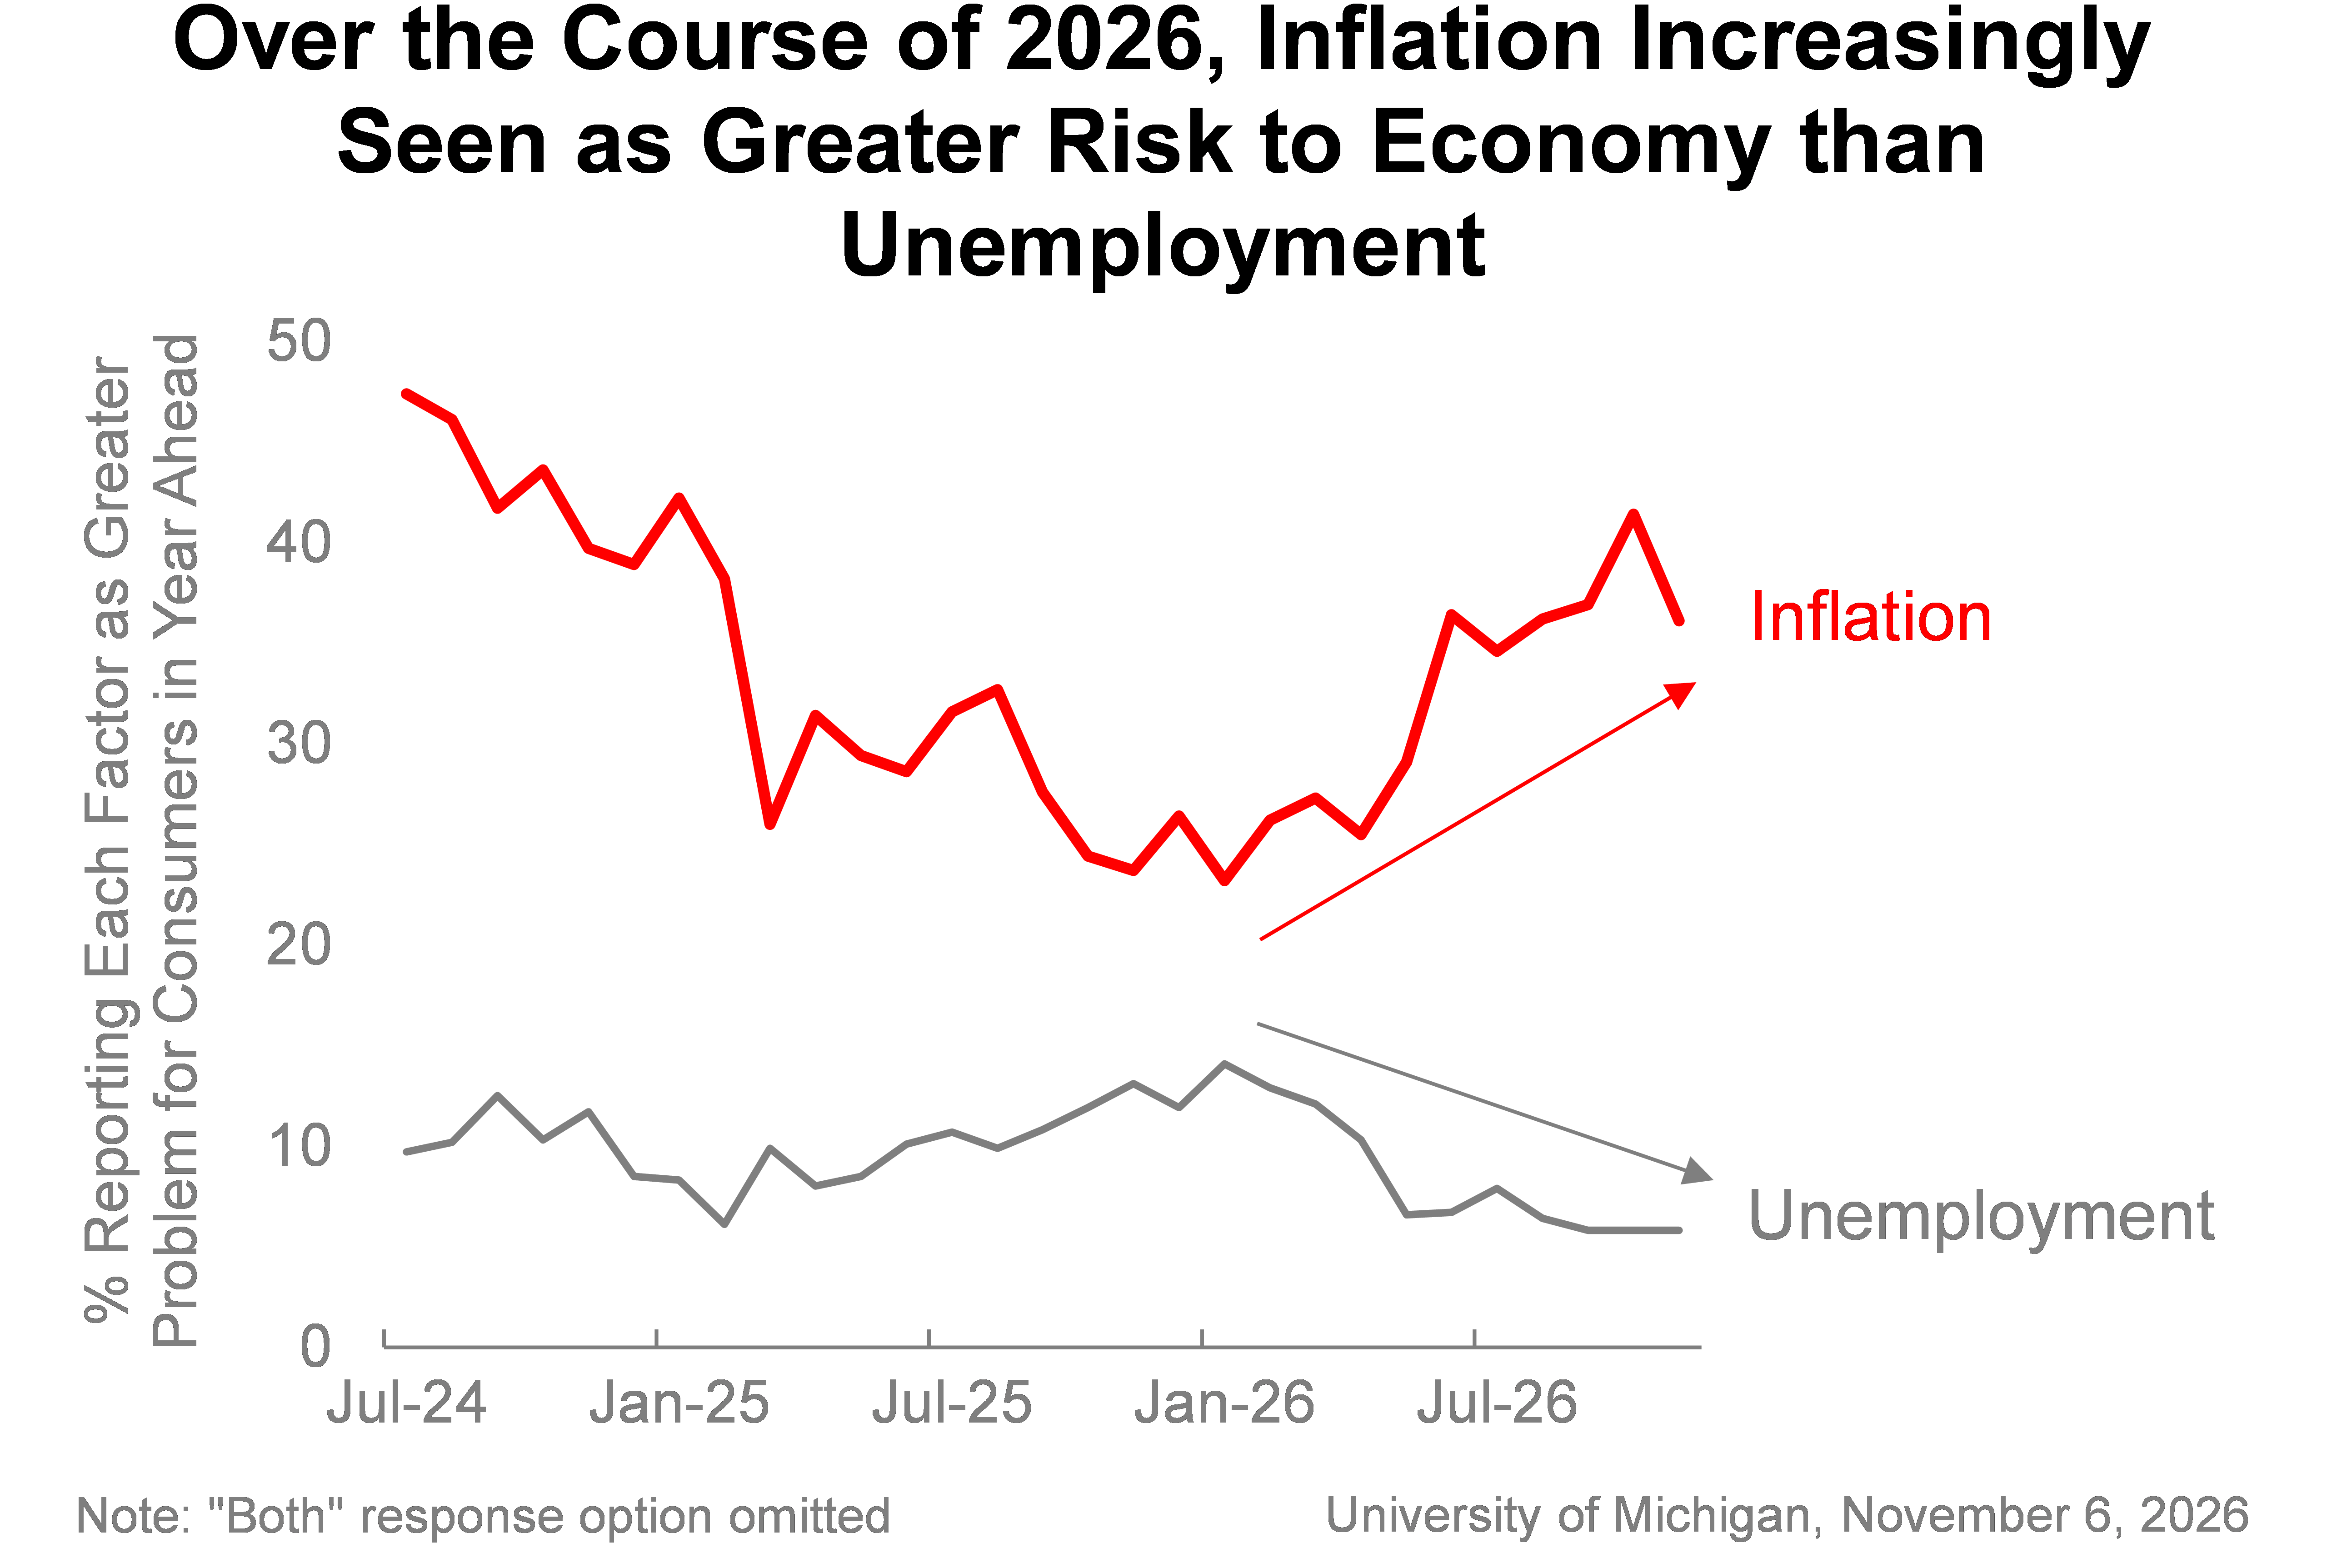
Consumer sentiment ticked up about 6% in the preliminary read. Modest improvements in multiple domains, including expected personal finances and business conditions, were concentrated primarily among independents. While sentiment lifted for lower- and middle-wealth consumers, it fell 5% for those with the largest stock portfolios in the wake of a relatively turbulent period in stock markets. Moreover, consumers’ comments revealed growing anxiety over a possible AI bubble. AI worries, however, were dwarfed by cost of living concerns, which continue to be at the forefront of consumers’ minds across the population. About 57% spontaneously mentioned that their living standards have been eroded by high prices, the highest seen since May and up from 46% in February, just prior to the Iran conflict. Despite this month’s improvement, sentiment is down 10% from February. Interviews for this release were conducted between October 20 and November 2. In the two months leading into the election, more than two-thirds of consumers expected Democrats to win the House, and over half anticipated the same for the Senate (see the October 30th special report on election expectations).
Year-ahead inflation expectations declined from 4.7% last month to 4.3% this month. Although the current reading is the lowest since August, it remains substantially above the 3.4% seen in February before the Iran conflict began, along with all 2024 readings. Long-run inflation expectations inched down from 3.5% in October to 3.4%, notably higher than their 2024 range of 2.8% to 3.2%.
Year-ahead inflation expectations declined from 4.7% last month to 4.3% this month. Although the current reading is the lowest since August, it remains substantially above the 3.4% seen in February before the Iran conflict began, along with all 2024 readings. Long-run inflation expectations inched down from 3.5% in October to 3.4%, notably higher than their 2024 range of 2.8% to 3.2%.